Authorization Holds And Balance
An authorization hold is a temporary reservation of funds triggered when a merchant asks your card network and issuer to approve a transaction. The merchant often does this before the final amount is known, such as at a hotel check-in, a car rental counter, or a restaurant where the tip is added later. Your bank or card issuer may show the hold as a pending transaction, which can reduce your “available balance” even though the final charge has not posted.
On credit cards, a hold can reduce your available credit limit and may also affect minimum payment calculations depending on how your issuer reports pending items. On debit cards, holds can reduce your available balance and sometimes your ability to complete other purchases, even when the underlying account balance remains unchanged. I’ve seen issuers label these items as “pending,” “authorization,” or “card verification,” and the wording varies by app version—one bank’s app showed “Authorization Pending” in early 2026, which helped me tell it apart from a posted charge.
Holds are not the same as fraud alerts. A fraud alert typically blocks transactions until you verify activity, while an authorization hold is a normal part of payment processing. The hold usually clears when the merchant submits the final transaction for settlement, or when the authorization expires if the merchant never completes the sale. The timing depends on merchant behavior, network rules, and issuer policies.
What People Get Wrong
Many people treat a pending charge as if it already settled, then panic when the final amount differs. A common example is a restaurant where the card is authorized for the pre-tip amount, and the final charge posts after the tip is added. Another example is gas stations that authorize a fixed amount at the pump, then post the actual total after you finish fueling. The pending amount can look “too high” until the final settlement arrives.
People also assume that the posted balance and available balance should match at all times. Issuers track multiple concepts: ledger balance (what has posted), available balance (what you can spend right now), and sometimes credit line usage. A hold can reduce available funds without changing the ledger balance. That’s why your app may show two different numbers that feel contradictory.
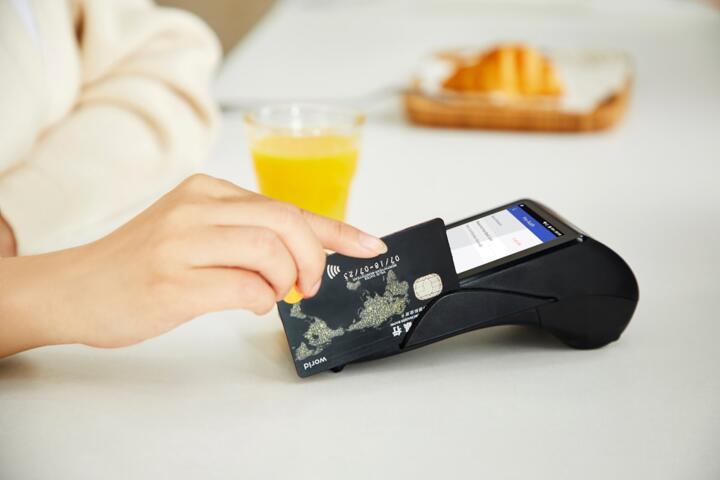
Supporting systems create these differences. Card payments involve the merchant’s payment terminal, the merchant’s acquiring bank, the card network, and your issuing bank. The merchant sends an authorization request, then later sends a clearing/settlement message with the final amount. If the merchant delays settlement, the hold can linger longer than expected. If the merchant reverses the authorization, the hold may release sooner, but reversals also depend on message timing across the chain.
Another misconception involves “authorization reversal” messages. Some merchants request a reversal when the final amount is lower, while others simply submit a new final amount that supersedes the earlier authorization. That difference can change how quickly the pending item disappears. Your issuer may still show the pending item until it receives the reversal or until the authorization expires.
How To Reduce Balance Surprises
Read Pending vs Posted
Start by separating pending items from posted transactions in your app or statement. Pending items usually show a date like “pending” or “authorization,” and they may disappear or change after settlement. Posted transactions show a completed posting date and typically remain visible with the final amount. If your app shows both a pending authorization and a later posted charge for the same merchant, the pending item is usually the earlier reservation that cleared after settlement.
Use the merchant name and transaction amount to match them. For example, a hotel may show a pending “Room Authorization” for a rounded estimate, then later post “Hotel Stay” for the exact total. If you see a pending charge that never posts and never reverses, it may still clear when the authorization expires, which can take longer than people expect.
Plan Around Typical Hold Timing
Hold duration varies, but many authorizations clear within a few business days after the merchant submits settlement. Some categories—like car rentals and hotels—can involve longer holds because the final amount depends on incidentals, deposits, or final billing. If you need to rely on your balance for another purchase, treat pending holds as “not yet spendable” until they clear.
As a practical habit, check your available balance after major holds post and after weekends. I’ve noticed that pending items often persist through a weekend and then update mid-week, which aligns with settlement and batch processing schedules. Your issuer’s help pages may list ranges, but they often avoid a single guaranteed number.
Use Receipts And Merchant Details
When the pending amount differs from your receipt, compare the authorization description. Gas stations often authorize an estimated amount at the pump and then post the final total after you pay inside or after the pump closes. Hotels may authorize a deposit plus estimated taxes, then later post the final bill. If you paid with a debit card, the hold can be larger than the final charge because deposits and incidentals are treated differently from final consumption.
If you see an authorization for an amount you did not expect, gather the receipt, the merchant location, and the date/time. Merchant disputes are easier when you can point to the exact authorization record your issuer shows as pending.
Contact The Issuer With Evidence
If a hold appears stuck beyond the timeframe you expected, contact your card issuer using the number on the back of your card or through the secure in-app messaging. Ask whether the authorization is still active, whether a reversal was received, and when it is expected to expire. Avoid sending sensitive card numbers through email or chat unless the issuer’s channel explicitly supports it.
For debit cards, ask whether the hold is reducing available balance due to an active authorization or due to a separate pending transaction. For credit cards, ask how the pending item affects your available credit and whether it will be reversed or replaced by a final settlement.
Educational Case Examples
Case 1: Restaurant tip adjustment. A customer pays $42.10 at a restaurant with a debit card. The terminal authorizes $42.10 as a pending transaction. After the meal, the tip is added, and the final posted charge becomes $52.10. The pending item disappears once the final settlement posts, and the available balance returns to normal after posting.
Case 2: Hotel deposit and final bill. A customer checks into a hotel and sees a pending charge labeled “Hotel Authorization” for $300 on a credit card. The hotel later posts the final bill for $268 plus taxes. The pending authorization clears after settlement, and the credit line usage reflects the final posted amount. If the pending authorization remains after the checkout date, the customer can ask the issuer whether the authorization has been reversed or is waiting to expire.
Hold vs Posted: Quick Checklist
| Item You See | What It Usually Means | What To Do | Typical Outcome |
|---|---|---|---|
| Pending authorization | Issuer reserved funds while merchant finalizes amount | Treat as unavailable; wait for settlement or reversal | Clears when final charge posts or authorization expires |
| Pending card verification | Small test charge or verification request | Confirm it matches merchant and amount; monitor for reversal | Often reverses without a final charge |
| Posted transaction | Merchant settled and issuer recorded final amount | Reconcile against receipt; dispute if wrong | Stays on ledger until resolved by refund/chargeback |
| Hold persists unusually long | Authorization not reversed or settlement delayed | Ask issuer if authorization is active; check merchant status | Clears on reversal or expiration; may require follow-up |
Step-by-step checklist:
- Open your issuer app and filter by “pending” and “posted.”
- Match the merchant name and date/time to your receipt or confirmation email.
- Check whether the pending amount later changes into a posted charge for the same merchant.
- Track the hold through business days, not calendar days, since settlement batches often run on schedules.
- If the hold remains beyond the timeframe your issuer states, contact the issuer with the transaction ID shown in the app.
Common Mistakes To Avoid
One mistake is budgeting based on ledger balance while ignoring available balance. If a debit hold reduces available funds, you can trigger declined transactions or overdraft fees even when the ledger balance looks fine. Another mistake is assuming a pending charge will always reverse automatically within a predictable window. Merchant settlement delays and reversal timing can stretch the hold.
People also dispute the wrong item. If you dispute a pending authorization that later posts correctly, you can create extra back-and-forth. Dispute the final posted charge when it exists, or ask the issuer whether the pending item is expected to reverse before filing a formal dispute.
Another practical error involves using the wrong card channel for documentation. If you pay by card in a hotel or rental, keep the receipt and any confirmation number. Many issuers ask for details tied to the authorization record, and the app’s transaction ID can speed up the search. I once watched a friend try to dispute a hotel charge using only a bank statement line item; the issuer asked for the authorization date and merchant reference, which were on the receipt.
Finally, avoid sharing full card numbers in support messages. Use the issuer’s secure messaging and provide only the transaction details they request. That reduces risk while still giving the issuer enough information to investigate.
FAQ
How long do card holds last?
Holds often clear within a few business days after the merchant submits settlement, but timing varies by merchant type and issuer policy. Hotels and car rentals can take longer because final amounts depend on incidentals and billing cycles.
Do authorization holds count as purchases?
They count as reserved funds, not final purchases, until they post as a settled transaction. Your app may show them as pending and reduce available balance before the final amount is recorded.
Why is the pending amount different?
Merchants may authorize an estimated amount when the final total is unknown, such as tips, deposits, or fuel estimates. The final posted charge reflects the settled amount after the merchant completes billing.
Can a hold cause overdraft or declines?
Yes for debit cards, because holds can reduce available balance used for transaction approvals. If you rely on available balance, a hold can lead to declines even when the ledger balance looks sufficient.
What should I do if a hold never clears?
Check whether a final posted charge appeared for the same merchant. If the pending item remains beyond the timeframe your issuer states, contact the issuer and ask whether the authorization is still active or expected to expire, then request a transaction reference review.
Author's Insight
Card authorization holds come from a real payment sequence: authorization requests reserve funds, then settlement messages finalize the amount. The same merchant can produce different pending amounts because deposits, tips, and estimates change after the initial authorization. Issuers display holds differently across apps, so “available” and “posted” numbers can diverge for a short period. When holds linger, the most reliable path is to match the authorization to your receipt and ask the issuer whether the authorization is active, reversed, or waiting to expire.
Key Takeaways
- Pending authorization holds reserve funds and can reduce available balance before the final charge posts.
- Restaurants, hotels, car rentals, and gas stations commonly authorize estimates that later settle to a different amount.
- Use your issuer app to distinguish pending from posted transactions, then reconcile against receipts.
- If a hold persists beyond the issuer’s stated timeframe, contact the issuer with the transaction details shown in the app.